A contract records intent; it does not rewrite reality
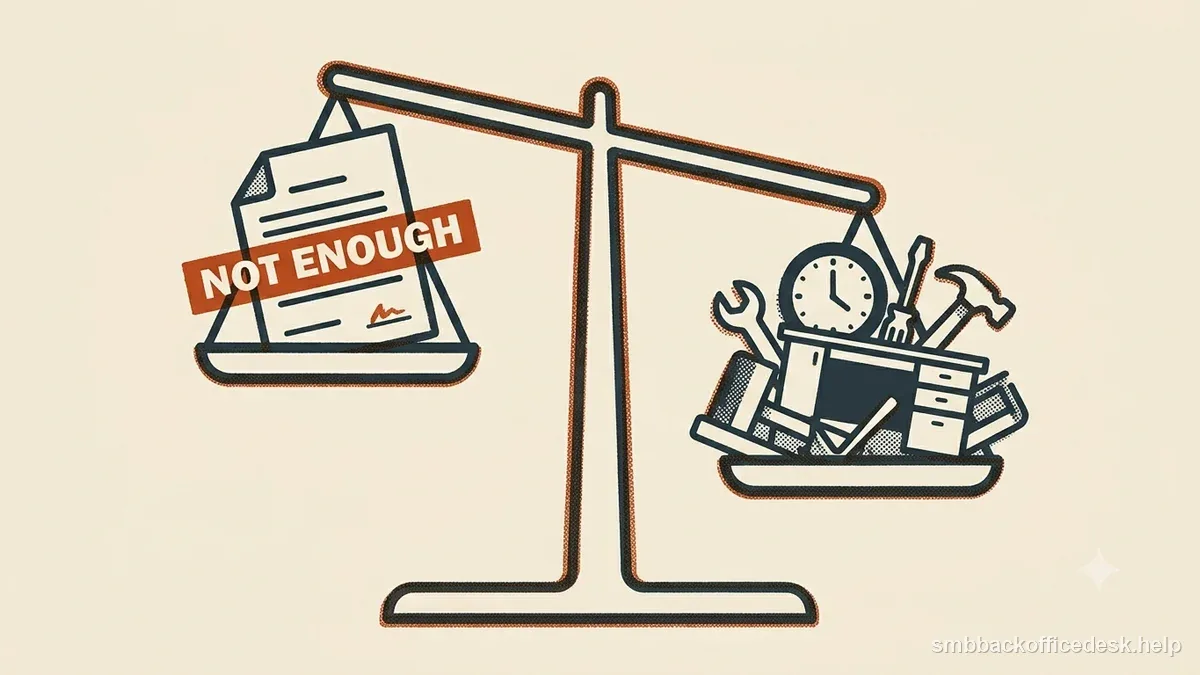
An agreement titled “Independent Contractor Agreement” is useful business documentation, but the title does not decide federal employment-tax status. The IRS looks at the actual relationship through behavioral control, financial control, and the type of relationship. A clause saying “contractor controls all methods” carries limited weight if managers assign fixed hours, prescribe procedures, approve every absence, and supervise the worker like staff.
The agreement still matters: it can show the parties’ stated intent and define scope, payment, confidentiality, ownership, and remedies. But the IRS says a contract label alone is insufficient. Under the FLSA, signing an independent-contractor agreement does not settle employee status either; the economic reality of the work matters. State laws may apply different tests.
Review clauses that affect the facts
Read the agreement for scope, method, schedule, equipment, expenses, assistants, outside clients, payment, profit and loss, benefits, term, and termination. Then ask how each term works in practice.
A project agreement can define a result, acceptance criteria, a deadline, and a payment milestone while leaving the contractor room to choose how to do the work. A clause requiring daily attendance, permission for ordinary schedule changes, company-provided equipment, exclusive service, or indefinite renewal describes a different arrangement. None is automatically decisive; the whole relationship and applicable law control.
Some policies serve a legitimate purpose. Data security, safety, confidentiality, licensing, and customer-access rules may be needed for the project. The classification question is whether the business is setting necessary boundaries or directing the manner and means like it would for staff. Copying an employee handbook wholesale can create restrictions that the actual project does not need.
Compare the paper to five real records
Review the agreement beside records that show how work actually happens:
1. Calendar and scheduling records show who sets working time and approves absences. 2. Task instructions and messages show whether the business controls methods or defines deliverables. 3. Expense and equipment records show who pays for tools, materials, workspace, and business costs. 4. Invoices and pricing history show how fees are negotiated and whether the worker can manage profit or loss. 5. Customer and marketing evidence shows whether the worker offers similar services in an independent market.
Mark contradictions and explain them. If the agreement permits subcontracting but managers require the work to be done personally, the practice matters. If the document says the worker supplies equipment but the company provides every specialized tool, record what is actually used and why. A mismatch is a prompt to review the facts, not a formula that decides status by itself.
| Agreement | Actual practice | |
|---|---|---|
| Schedule | Autonomy described | Manager controls hours or absences |
| Methods | Contractor controls means | Detailed procedures and supervision |
| Business costs | Worker bears costs | Company supplies tools and expenses |
| Outside work | May serve other clients | Policy or practice prevents it |
Avoid clauses that promise a classification result
A declaration that the worker “is solely responsible for all manner and means” does not help if an operating manual dictates every step. A statement allowing other clients is weak evidence if an approval rule or workload makes outside work impractical. Likewise, an LLC, EIN, W-9, 1099, or tax-indemnity clause does not transfer the government’s classification decision to the worker.
Do not use indemnity language as a substitute for correct classification or assume an entity structure changes the underlying service relationship. These terms may serve other contractual purposes, but they cannot make inconsistent working practices disappear.
Fix the relationship before polishing the document
When the contract and practice diverge, decide which reflects the business’s real operational need. If the company genuinely needs fixed coverage, continuous supervision, required methods, or ongoing integration into ordinary staff operations, evaluate employee treatment under each applicable law. If the work is genuinely an independent project, managers may be able to define deliverables, interfaces, security requirements, deadlines, and acceptance criteria without micromanaging the contractor’s business methods.
Do not remove safety, privacy, or other necessary controls just to make a file look like a contractor relationship. Classification should follow a lawful operating model, not cosmetic evidence engineering. If practice cannot change, update the classification analysis and the contract to match the real arrangement.
Recheck every legal layer
A review under IRS common-law rules does not complete an FLSA or state-law review. The Department of Labor’s February 2026 FLSA action is a proposed rule, not a final rule; DOL says it is no longer applying the 2024 rule in its investigations. Check DOL’s current status and the law that applies to the work period before relying on an old checklist. Court cases and state rules may require a separate analysis.
California’s ABC test, for example, asks whether all required conditions are met unless an exemption or alternative test applies. Other states use different standards, and some locations may require a written agreement with specific terms for certain freelance work. Check the worker’s location and the relevant statute before reusing one national form. Form SS-8 can request an IRS determination of federal tax status, but it may take at least six months and does not decide every other law.
Review when the facts change
A calendar reminder can prompt a review, but a reminder every ninety days is only an optional administrative checkpoint, not a legal deadline or safe harbor. Revisit the relationship when the scope expands, a project becomes recurring work, supervision or hours change, the worker moves, the agreement renews, or the business adds exclusivity or employee-like benefits.
Compare termination rights and outside-client terms with actual practice. A narrowly tailored conflict restriction may protect confidential project information; a broad ban on serving other customers can conflict with evidence that the worker operates an independent business. A defined project with breach remedies also differs from day-to-day work that either side can end at any moment. Record what changed, when it changed, and whether the current classification and contract still describe the arrangement.
- At startRecord role, scope, and operating model.
- When facts changeRecheck hours, supervision, tools, exclusivity, and duties.
- After reviewUpdate classification and agreement if facts shifted.