A chargeback notice rarely says "the customer says the product wasn't as described." It says something like "Reason Code 85" or "13.1" or "C08," and a merchant who does not know what that number means will waste the response window looking in the wrong place. Each card network keeps its own numbering system, the same underlying complaint can carry a different code on different networks, and the numbering has changed over time as networks consolidated categories. This guide is a map from the number on the notice to the actual factual question being asked, not a full response playbook — the ten guides elsewhere on this site cover writing the actual evidence for each scenario.
Three separate numbering systems, one underlying set of complaints
Visa, Mastercard, and American Express each publish separate dispute identifiers, and a processor may show both a network code and its own plain-language label. There is no universal cross-network number. For example, current Visa Dispute Condition 13.6 means Credit Not Processed; Mastercard uses numeric message reason codes such as 4860 in the dual-message system, while Amex uses C02 for Credit Not Processed. C08 is Amex Goods/Services Not Received, not a credit-not-processed code. Use the network and exact label printed on the live notice as the starting point.
Codes can depend on processing system and region. Visa examples: 13.1 not received, 13.2 canceled recurring, 13.3 not as described/defective, 13.6 credit not processed, 13.7 canceled merchandise/services, and 12.6 duplicate/paid by other means. Mastercard is consolidating legacy codes, though older ones may still appear. Amex distinguishes C02 credit, C08 nonreceipt, C28 recurring, C31 not as described, and C32 damaged/defective; C04, C05, and C18 are narrower credit cases.
Why the exact code changes what evidence matters
The code is the network's shorthand for the specific factual question the cardholder or issuer is asking. A "credit not processed" code asks whether a refund the merchant agreed to (or was required to make) was actually issued and posted. It does not ask whether the original sale was valid, so proof of the original transaction is not the evidence that resolves it — proof of the refund, or proof no refund was owed, is. A "not as described" code asks about the condition or nature of what was delivered relative to the listing, which calls for product specifications, photos, and support communications, not a refund ledger.
A delivery receipt does not answer a not-as-described claim. Match each document to the coded question, and read the notice's plain-language label because processors may show their own summary beside the network code.
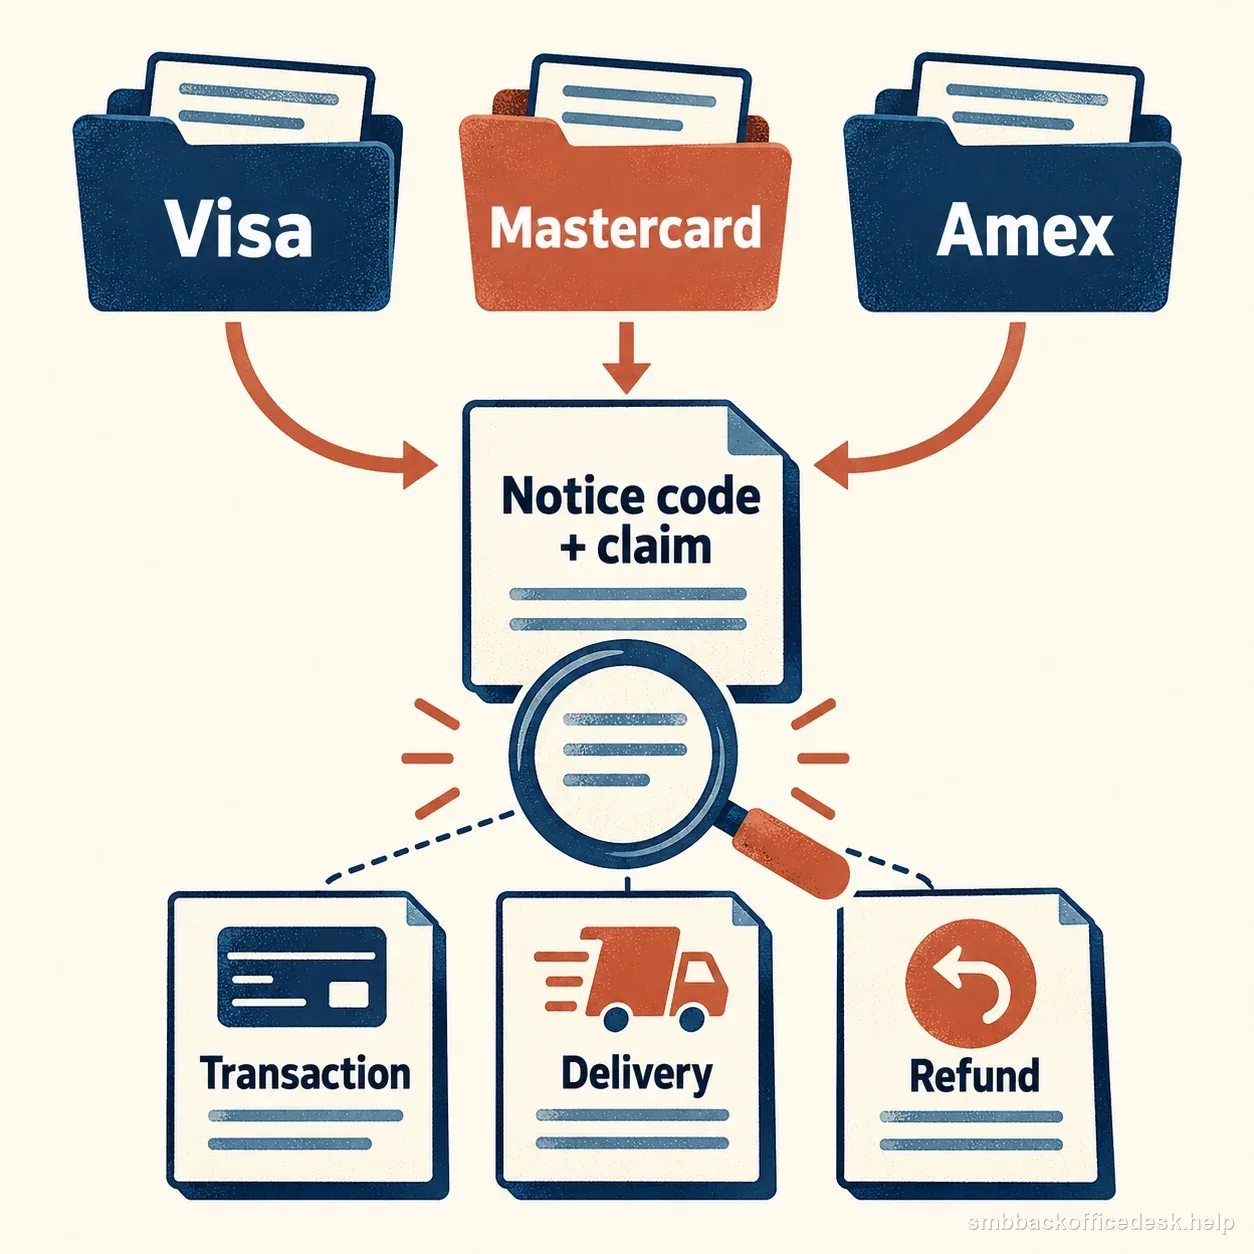
Start with the network and exact notice label, then gather only records that answer that claim.
A representative mapping (verify the live notice)
| Dispute category | Visa (current condition) | Mastercard (message reason code examples) | Amex (code) |
|---|---|---|---|
| Credit not processed | 13.6 | 4860 (legacy code; 4853 may be used as the consolidated cardholder-dispute code) | C02 |
| Goods/services not received | 13.1 | 4855 (legacy code; 4853 may be used as the consolidated cardholder-dispute code) | C08 |
| Not as described / defective | 13.3 | 4853; 53 for some U.S. debit transactions | C31 (not as described); C32 (damaged/defective) |
| Canceled recurring transaction | 13.2 | 4841 (legacy code; check the current notice and region) | C28 |
| Duplicate charge / paid by other means | 12.6 | 4834/34 (Point-of-Interaction Error; includes duplicate debit and paid with another method) | C14 is paid by other means; do not treat it as a universal duplicate code |
| Card-not-present fraud | 10.4 | 4837 | F29 |
| Amex reversal decision | — | — | S01 (Chase/processor guide: reversal request denied) |
If your notice shows Amex S01, treat it as a processor-described reversal decision, not a new customer-dispute category: Chase's reason-code guide labels S01 “Reversal Request Denied.” American Express's published merchant guide lists its underlying chargeback categories under codes such as C02, C08, F29, and M01, and does not list S01 in that code table. Read the case history and current reply-by date in your merchant or processor portal before deciding whether any action remains.
Use the table as an orientation, not a universal crosswalk. Mastercard 4853 is the consolidated Cardholder Dispute code; legacy 4841, 4855, and 4860 may still appear by region or processing system. Amex C04, C05, and C18 are narrower credit cases. Confirm the exact code and label in the live processor notice and applicable network guide before assembling evidence.
The number tells you the network's theory, not the customer's whole story
A dispute can be filed under the wrong code — a cardholder who actually never received the item might get coded as "not as described" by a call-center agent who typed the wrong category, or a bank might apply a fraud code when the real issue is a service cancellation the merchant never processed. If the evidence you have clearly answers a different, closely related question than the one the code technically asks, include both: address the coded question directly, and note the discrepancy with supporting facts. Do not simply argue that "the code is wrong" without also answering the substance, because a technical objection alone rarely overturns a dispute.
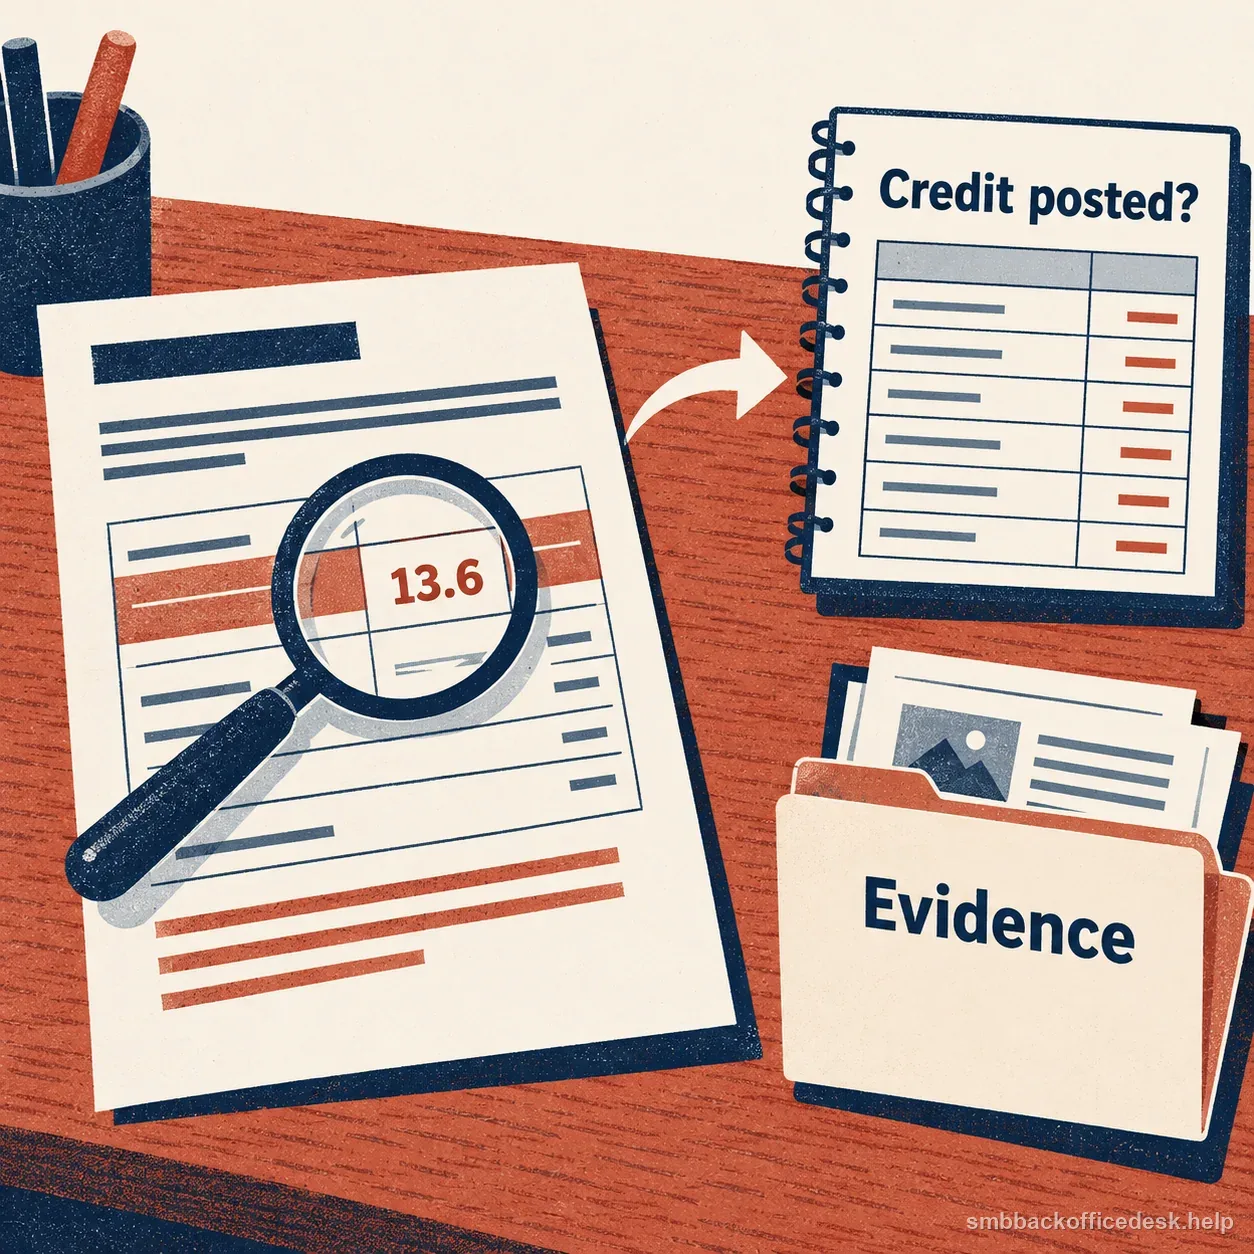
This example focuses the review on whether the promised credit actually posted.
Filing and response windows differ by network too
Just as the codes differ, so do the clocks. Visa, Mastercard, and Amex each set their own cardholder filing windows and merchant response windows, and those windows can also vary based on the specific reason code and whether it is a first chargeback, a pre-arbitration, or arbitration stage. The deadline printed on the actual processor notice controls the immediate task — a general "60 days" or "120 days" figure repeated from an old article is not reliable enough to build a real deadline around. Calendar the date on the current notice the same day it arrives.
What to do with the code before you touch a single document
Write down four things before pulling any evidence: the exact code and its label from the current notice, the network, the transaction amount and date, and the response deadline. Then open this site's scenario guide that matches the label — "not as described," "not received," "duplicate processing," "credit not processed," "canceled recurring," or the fraud/card-not-present guide — and follow its evidence checklist. The code is the entry point into the right process, not the process itself.
When the code does not map cleanly to any scenario guide
Some codes are narrow or network-specific enough that no single-scenario page will match exactly — authorization-related codes, processing-error codes tied to currency or account-number mismatches, or codes specific to a card-present terminal failure. In those cases, read the network's own current description of the code closely, gather the transaction-processing records that speak directly to that description, and consider requesting written clarification from the acquirer or processor about which evidence they expect. Guessing at a mismatched evidence type wastes the response window; a short clarifying question to the payment processor rarely does.
Illustrative $240 credit-not-processed review
Suppose a customer bought a $240 service, the business agreed in writing to return $60 for one unused portion, and a later notice shows an Amex C02 credit-not-processed reason. Start with the amount and transaction the issuer is actually disputing. Match the $60 promise to the refund entry, payment processor reference, and settlement record; keep the original $240 sale receipt only as context. The arithmetic is simple: $240 original charge minus the agreed $60 credit leaves $180 that was not part of that refund promise. That does not decide whether the remaining $180 is valid or whether the dispute will be resolved for the merchant. It only prevents the response packet from treating the promised credit as if it covered the entire sale.
If the ledger says the $60 refund was created but the processor record shows it was still pending, do not describe it as completed. Record the status, check whether the case notice seeks $60 or another amount, and follow the processor's current response instructions. This example is illustrative; actual network labels and case handling can vary by region and processor.
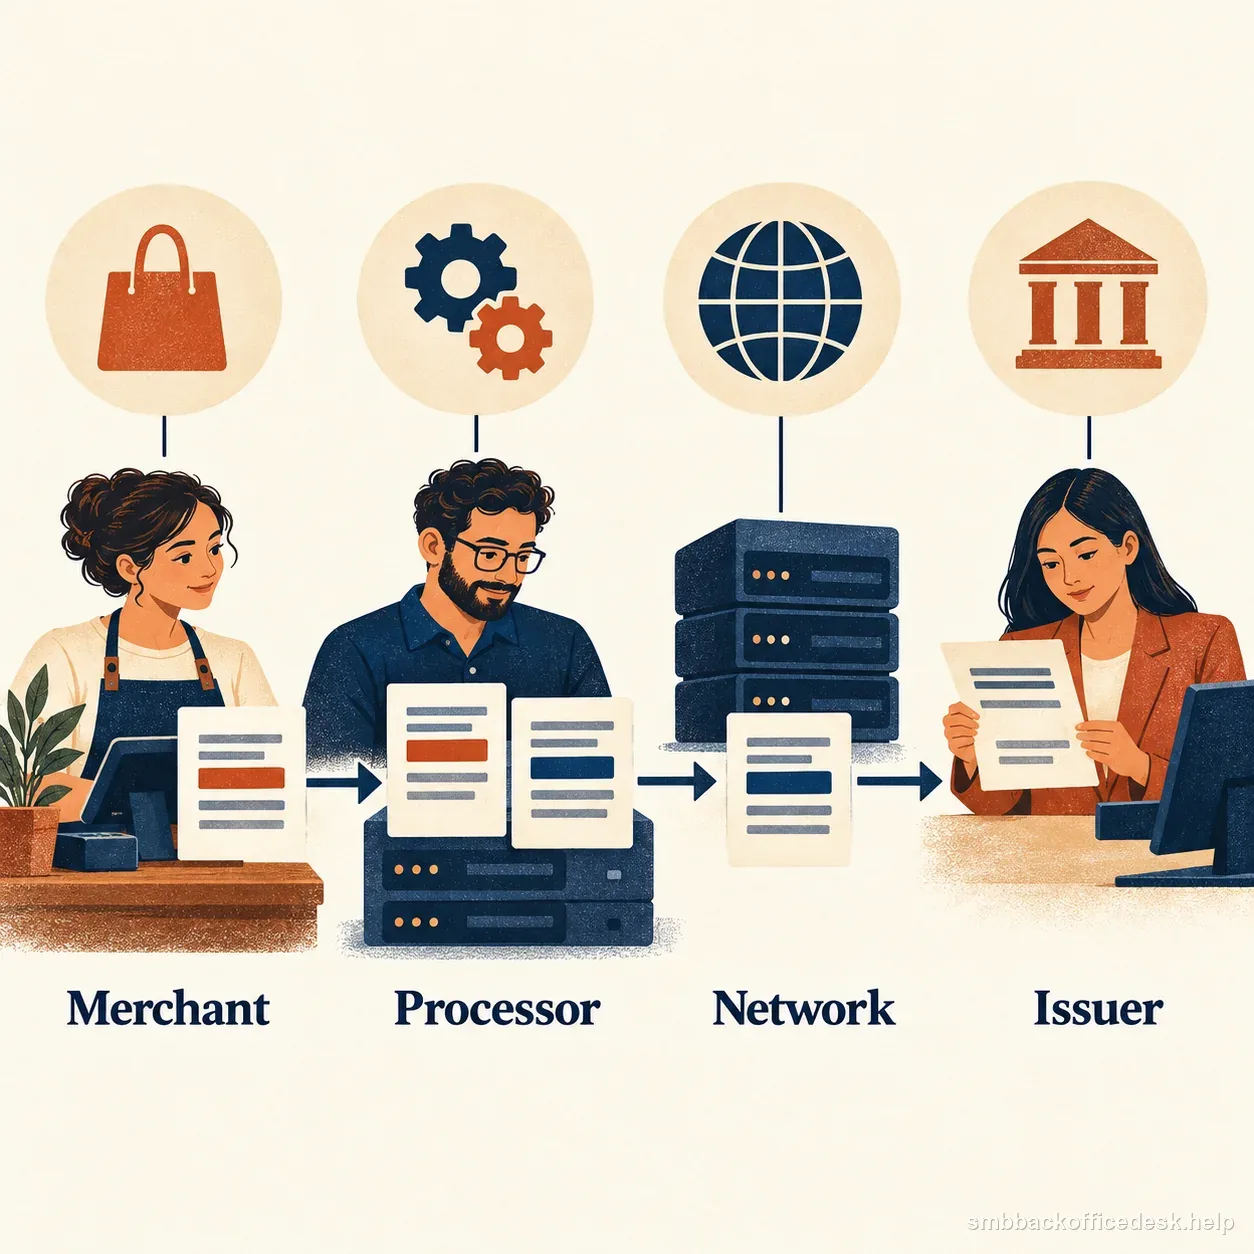
Illustration separates the merchant, processor, card network, and issuer roles that may appear in a dispute-code workflow.
Keep a running log by code, not just by dispute
If chargebacks recur, track them by network and code rather than only by total count. A cluster of "credit not processed" disputes usually points to a refund-processing delay inside the business, while a cluster of "not as described" disputes usually points to a listing or fulfillment problem. The code-level pattern is often more actionable than an aggregate chargeback-rate number, because it tells you which operational process to fix first.
- First chargebackRecord network, code, and stated reason.
- EscalationRead the new notice; code may change.
- ResponseMatch packet to current stage and evidence standard.
What changes when a case escalates past the first chargeback
A dispute can move through chargeback, pre-arbitration, and arbitration, but the escalation path and permitted reason-code changes depend on the network, region, and case. Do not assume a code will change or stay fixed. Record the exact code and description shown at each stage, check the new notice and its response deadline, and update the evidence packet if the stated issue or required documents differ.
Quick reference for the situations above:
| If you see | What to do |
|---|---|
| An unfamiliar code | Write down the exact code and its label from the current notice, the network, the transaction amount and date, and the response deadline before pulling any evidence |
| A code with no matching scenario guide, such as authorization-related codes, processing-error codes tied to currency or account-number mismatches, or card-present terminal failures | Read the network's own current description, gather the processing records that speak to it, and ask the acquirer or processor in writing which evidence they expect |
| A code that looks wrong for the facts | Answer the coded question directly and note the discrepancy with supporting facts; do not argue only that the code is wrong |
| Amex S01 | Treat it as a processor-described reversal decision, then read the case history and current reply-by date in your portal before deciding whether any action remains |
| A legacy Mastercard code such as 4841, 4855, or 4860 | Check the current notice and region; 4853 is the consolidated Cardholder Dispute code |
| A deadline you are unsure about | Use the date on the current notice and calendar it the same day; a general "60 days" or "120 days" figure from an old article is not reliable |
| A case that moves to pre-arbitration or arbitration | Record the exact code and description at each stage, check the new notice and its deadline, and update the evidence packet if the stated issue or required documents differ |